ACORD 35 Cancellation Request / Policy Release: How to Fill It Out (2016/03 Edition Guide)
ACORD 35 is the standard Cancellation Request / Policy Release form used by US insurance agencies and carriers to document a policyholder's instruction to cancel a policy. It records the policy, the exact date and hour cancellation takes effect, the reason, how the return premium is calculated, and who must be notified — and, when the original policy can't be returned, a signed policy release confirming the insured gives up claims for losses after cancellation. The edition most agencies and carriers use today is ACORD 35 (2016/03).
In this guide
- What ACORD 35 is and when to use it
- Editions: 1/97, 2011/09 and 2016/03
- The form, section by section
- How to fill it out, step by step
- Pro rata, short rate and flat cancellation — with calculations
- Completed example
- Policy release vs cancellation request
- State-specific notes (New York, New Hampshire)
- Common mistakes and E&O tips
- FAQ
What Is the ACORD 35 Form?
ACORD 35 is one of the standardized forms published by ACORD, the non-profit that sets data and form standards for the insurance industry (see what is ACORD). It is the agency's written record that the named insured asked for a policy to end, and it works for both personal lines (auto, homeowners, renters) and commercial lines (general liability, commercial auto, property and more).
When to use ACORD 35
- Insured-requested cancellation — the vehicle was sold, the home was sold, the business closed, or coverage was placed elsewhere.
- Policy not taken — the insured never accepted the policy, so it is cancelled from inception.
- Policy rewritten — replaced by a new policy with the same or a different carrier.
- Original policy can't be returned — the insured signs the policy release statement instead of returning the policy.
When not to use it: cancellations started by the insurer — for non-payment or underwriting reasons — are normally made with the carrier's own notice of cancellation, which must meet state-mandated notice periods. ACORD 35 documents the insured's request; it is not a substitute for a carrier's statutory notice.
ACORD 35 Editions: Which Version to Use
| Edition | Notes |
|---|---|
| ACORD 35 (1/97) | Older edition, still seen in legacy files and some downloads |
| ACORD 35 (2011/09) | Added a fuller request/release distribution list (insured, loss payee, mortgagee, lienholder, company, finance company) and the New York auto notice |
| ACORD 35 (2016/03) | The edition most commonly in use; includes a New Hampshire note on the lienholder field and a remarks section that can be continued on ACORD 101 |
The edition date is printed in the bottom corner of the form. Carriers can specify which edition they accept, and ACORD stops reviewing outdated editions for regulatory compliance — so use the current edition from your agency management system or the ACORD forms portal, and check the carrier's requirements.
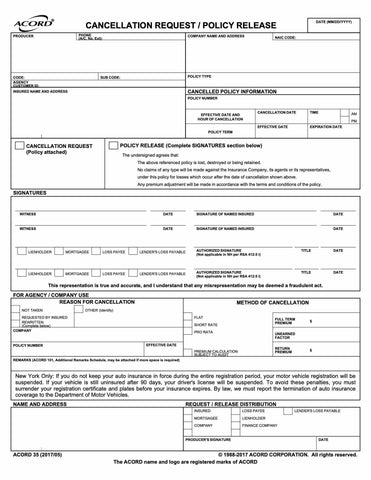
ACORD 35 Form Sections at a Glance
| Section | What goes in it |
|---|---|
| Date and producer | Form date; agency name, address, phone, agency code, sub code and customer ID |
| Company | Insurer's name, address and NAIC code |
| Insured | Named insured's full legal name and mailing address |
| Cancelled policy information | Policy type, policy number, policy term (effective and expiration dates) |
| Effective date and hour of cancellation | Cancellation date and time, with AM/PM |
| Request type | Cancellation request (policy attached) or policy release (complete statement section) |
| Reason for cancellation | Requested by insured, not taken, or rewritten (with replacement details), plus an explanation |
| Method of cancellation | Flat, pro rata or short rate |
| Policy release statement | Confirms the policy is lost, destroyed or being retained, and releases the insurer from losses after the cancellation date |
| Signatures | Named insured(s), witness(es) for a release, authorized company signature, producer's signature |
| For agency/company use | Full-term premium, unearned factor and return premium |
| Remarks | Extra detail; continue on ACORD 101 if needed |
| Name and address request/release distribution | Who receives copies: insured, loss payee, mortgagee, lienholder, company, finance company |
How to Fill Out ACORD 35: Step by Step
Step 1: Date and producer details
Enter the date the form is completed, then the agency's name, address and phone, agency code, sub code and the customer ID. Copy these exactly from your agency management system so they match the carrier's records.
Step 2: Insurance company and NAIC code
Enter the insurer's full legal name, address and five-digit NAIC code. The NAIC code is on the declarations page and in your state insurance department's company lookup.
Step 3: Insured name and address
Use the named insured exactly as shown on the declarations page — the full legal name for individuals, the registered legal name for businesses — and the current mailing address.
Step 4: Cancelled policy information
Enter the policy type (for example, personal auto or commercial general liability), the policy number and the policy term's effective and expiration dates. A single wrong digit can cancel the wrong policy, so double-check against the declarations page.
Step 5: Effective date and hour of cancellation
Enter the cancellation date and time and tick AM or PM. Most policies change at 12:01 AM standard time at the insured's address, so 12:01 AM is the usual choice. For auto policies with DMV reporting and property policies with a mortgagee, the exact date and time matter — confirm replacement coverage starts no later than this moment.
Step 6: Cancellation request or policy release
Tick Cancellation Request (Policy attached) if the original policy is being returned, or Policy Release if it is lost, destroyed or being retained — and then complete the policy release statement.
Step 7: Reason for cancellation
Tick Requested by insured, Not taken or Rewritten, and give a short, specific explanation — for example, “Insured request – vehicle sold” or “Insured request – covered elsewhere.” If the policy is rewritten, complete the replacement details. Use Remarks (or ACORD 101) for anything longer.
Step 8: Method of cancellation
Tick Flat, Pro rata or Short rate. The method is set by the policy terms, state rules and the carrier — not by the agency — so confirm it before submitting. See the calculations below.
Step 9: Policy release statement (if applicable)
When used as a release, the insured confirms the policy is lost, destroyed or being retained, and agrees that the insurer is released from liability for losses occurring after the cancellation date. Explain this to the insured before they sign.
Step 10: Signatures
- Named insured(s) sign and date. If there are two named insureds, get both signatures where the carrier requires it.
- Witness — when the form is used as a policy release, the insured should have a witness sign and date it before returning it to the agent.
- Authorized company signature and producer's signature as required by the carrier.
Agents should not sign on the insured's behalf. Many carriers accept e-signatures; keep the signature audit trail.
Step 11: For agency/company use — return premium
Enter the full-term premium, the unearned factor and the resulting return premium, or leave the section for the carrier to complete if that is its practice.
Step 12: Distribution
Tick every party who must receive a copy: insured, loss payee, mortgagee, lienholder, company and finance company. Lenders and premium finance companies usually have contractual rights to notice, so missing one can create an E&O exposure.
Pro Rata vs Short Rate vs Flat: Return Premium Calculations
| Method | What it means | Typically used when |
|---|---|---|
| Flat | Cancelled from the effective date; the full premium is returned | Policy not taken, or cancelled back to inception |
| Pro rata | Return premium exactly matches the unused days — no penalty | Insurer-initiated cancellations; many insured-requested cancellations where the policy or state rules require it |
| Short rate | Return premium is less than pro rata — the insurer keeps an early-cancellation charge | Some insured-requested mid-term cancellations, where the policy allows it |
Worked example
A 12-month policy runs from January 1 to December 31, 2026, with a full-term premium of $1,200. The insured cancels effective April 1, 2026, at 12:01 AM.
- Days in force: 90 (January 1 – March 31). Days unexpired: 275 of 365.
- Unearned factor = 275 ÷ 365 = 0.753
- Pro rata return premium = $1,200 × 0.753 = $904 (rounded)
- Short rate return premium: lower than $904 — the exact figure comes from the carrier's short-rate table or policy wording. For example, if the carrier's short-rate penalty is 10% of the pro rata return, the refund is about $814.
- Flat: would return the full $1,200 — only if the policy were cancelled back to January 1.
Minimum earned premiums, fees and audit adjustments (common on commercial policies) can reduce the refund further.
ACORD 35 Example: Completed Cancellation Request
Scenario: the insured sells their car and asks to cancel the personal auto policy. The original policy is being returned, the carrier cancels pro rata, and the car loan lender must be notified.
| Field | Entry |
|---|---|
| Policy type / number | Personal Auto / PA-1234567 |
| Policy term | 01/01/2026 – 12/31/2026 |
| Cancellation date and time | 04/01/2026, 12:01 AM |
| Request type | Cancellation Request (policy attached) |
| Reason | Requested by insured – vehicle sold |
| Method | Pro rata |
| Full-term premium / unearned factor / return premium | $1,200 / 0.753 / $904 |
| Distribution | Insured, company, lienholder |
| Signatures | Named insured; producer |
Policy Release vs Cancellation Request
| Cancellation request | Policy release | |
|---|---|---|
| Box to tick | Cancellation Request (policy attached) | Policy Release (complete statement section) |
| Original policy | Returned with the form | Lost, destroyed or being retained |
| What the insured confirms | Instruction to cancel from the stated date and hour | Instruction to cancel and release of the insurer from losses after the cancellation date |
| Witness | Not usually required | Insured should have a witness sign and date |
State-Specific Notes
- New York (auto): the form carries a New York notice. If auto insurance lapses during the registration period, the registration will be suspended; if the vehicle stays uninsured after 90 days, the driver's license will be suspended. Insureds should surrender their plates and registration before coverage ends, and insurers must report the termination to the DMV.
- New Hampshire: the 2016/03 edition marks the lienholder distribution as not applicable in New Hampshire, citing RSA 412:5 I.
- Other states: most states require insurers to report auto insurance terminations to the motor vehicle agency, and statutes set notice rules for insurer-initiated cancellations. Check the rules in the insured's state and the carrier's guidelines.
Common ACORD 35 Mistakes and E&O Tips
- Cancelling before new coverage starts: confirm the replacement policy is bound and effective no later than the cancellation date and hour.
- Verbal requests only: always get the insured's signed ACORD 35 (or written request) before cancelling.
- Wrong policy or wrong time: check the policy number, named insured and AM/PM against the declarations page.
- Missing distribution: lienholders, mortgagees, loss payees and premium finance companies must be ticked where they have an interest.
- Agency choosing the method: the carrier and policy decide flat, pro rata or short rate.
- Not following up: keep the signed form and the carrier's cancellation confirmation in the client file.
What Happens After You Submit ACORD 35
- The carrier reviews the form for completeness and processes the cancellation.
- The carrier issues a cancellation confirmation or endorsement to the insured and agency.
- Any return premium is calculated and refunded — or applied to a premium finance account.
- Required parties (lienholders, mortgagees, finance companies, and for auto the DMV where required) are notified.
ACORD 35 PDF
Most agencies generate ACORD 35 from their agency management system, which pre-fills policy data. You can also view a printable ACORD 35 form (PDF) — check the edition date in the bottom corner against your carrier's requirements.
Related Guides
- What is ACORD?
- How to write an insurance cancellation letter
- How to cancel Progressive insurance
- ACORD 80 form · ACORD 125 form · ACORD 27 form
ACORD 35 FAQ
What is the ACORD 35 form?
ACORD 35 is the standard Cancellation Request / Policy Release form used by US insurance agencies and carriers to document a named insured's request to cancel a policy. It records the policy, the date and hour of cancellation, the reason, the cancellation method, return premium and who must be notified.
What is the latest version of ACORD 35?
The edition most commonly in use is ACORD 35 (2016/03). Earlier editions include 2011/09 and 1/97. The edition date is printed on the form; use the current edition from your agency system or the ACORD forms portal and check which edition the carrier accepts.
What is the difference between a cancellation request and a policy release?
A cancellation request is used when the original policy is returned with the form. A policy release is used when the policy is lost, destroyed or being retained; the insured signs a statement releasing the insurer from liability for losses after the cancellation date, ideally in front of a witness.
What is the difference between pro rata and short rate cancellation?
Pro rata cancellation refunds the premium for every unused day with no penalty. Short rate cancellation refunds less than pro rata because the insurer keeps an early-cancellation charge, calculated from its short-rate table or policy wording. Flat cancellation returns the full premium from inception.
Can an insurance agent sign ACORD 35 for the insured?
No. The named insured should sign the cancellation request or policy release. The agent signs as producer. Signing for the insured without written authority creates errors and omissions exposure.
Is ACORD 35 used when the insurer cancels a policy?
Generally no. ACORD 35 documents the insured's request. Insurer-initiated cancellations, such as for non-payment, are made with the carrier's own notice of cancellation, which must meet state notice requirements.
This guide is for general information for insurance professionals and policyholders. Always follow the carrier's instructions and the rules of the insured's state. Last updated: September 2026.
2 comments
Featured product


Featured product


Popular posts

Featured product


FAQs
ACCA blogs
Follow these links to help you prepare for the ACCA exams
IFRS blogs
Follow these blogs to stay updated on IFRS
Formats
Use these formats for day to day operations
- Account closure format
- Insurance claim letter format
- Transfer certification application format
- Resignation acceptance letter format
- School leaving certificate format
- Letter of experience insurance
- Insurance cancellation letter format
- format for Thank you email after an interview
- application for teaching job
- ACCA PER examples
- Leave application for office
- Marketing manager cover letter
- Nursing job cover letter
- Leave letter to class teacher
- leave letter in hindi for fever
- Leave letter for stomach pain
- Leave application in hindi
- Relieving letter format
Interview questions
Link for blogs for various interview questions with answers
- Strategic interview questions
- Accounts payable interview questions
- IFRS interview questions
- CA Articleship interview questions
- AML and KYC interview questions
- Accounts receivable interview questions
- GST interview questions
- ESG Interview questions
- IFRS 17 interview questions
- Concentric Advisors interview questions
- Questions to ask at the end of an interview
- Business Analyst interview questions
- Interview outfits for women
- Why should we hire you question
leave application format
- Leave application for office
- Leave application for school
- Leave application for sick leave
- Leave application for marriage
- leave application for personal reasons
- Maternity leave application
- Leave application for sister marriage
- Casual leave application
- Leave application for 2 days
- Leave application for urgent work
- Application for sick leave to school
- One day leave application
- Half day leave application
- Leave application for fever
- Privilege leave
- Leave letter to school due to stomach pain
- How to write leave letter
Insurance blogs
- Sample letter of appeal for reconsideration of insurance claims
- How to increase insurance agent productivity
- UAE unemployment insurance
- Insurance cancellation letter
- Insurance claim letter format
- Insured closing letter formats
- ACORD cancellation form
- Provision for insurance claim
- Cricket insurance claim
- Insurance to protect lawsuits for business owners
- Certificate holder insurance
- does homeowners insurance cover mold
- sample letter asking for homeowner right to repair for insurance
- Does homeowners insurance cover roof leaks

X Days from Today

Form 8946 Guide for Indians Without SSN | PTIN
Form 8946 guide for Indian PTIN applicants Form 8946 for Indian Applicants Without SSN: PTIN Documents, Notary Rules...

6 Weeks From Today — What Date Is It? (Updated Daily)
6 Weeks From Today Six weeks from today is . That is exactly 42 calendar days from now,...
Admission cancel 11th class
Clearly, many thanks for the help in this question.
Leave a comment